Brent crude futures fell 1.1% to $114.05 a barrel by 0922 GMT, while US West Texas Intermediate crude declined 1.5% to $101.27. The retreat reversed part of the previous session’s gains as traders assessed the possibility of renewed negotiations alongside continuing risks to energy infrastructure and shipping routes.
Diplomatic activity helped temper market concerns. Reports indicated that US Vice President JD Vance had contacted an Iranian official, while Qatari mediators had presented Tehran with a draft agreement. Iran’s response remained mixed, although its foreign minister said diplomacy was still possible.
The prospect of negotiations has particular significance for energy markets because the conflict has disrupted supplies and heightened concerns around the Strait of Hormuz, a critical route for international oil and gas shipments. Any reduction in the risk of further escalation could ease the supply premium embedded in crude prices.
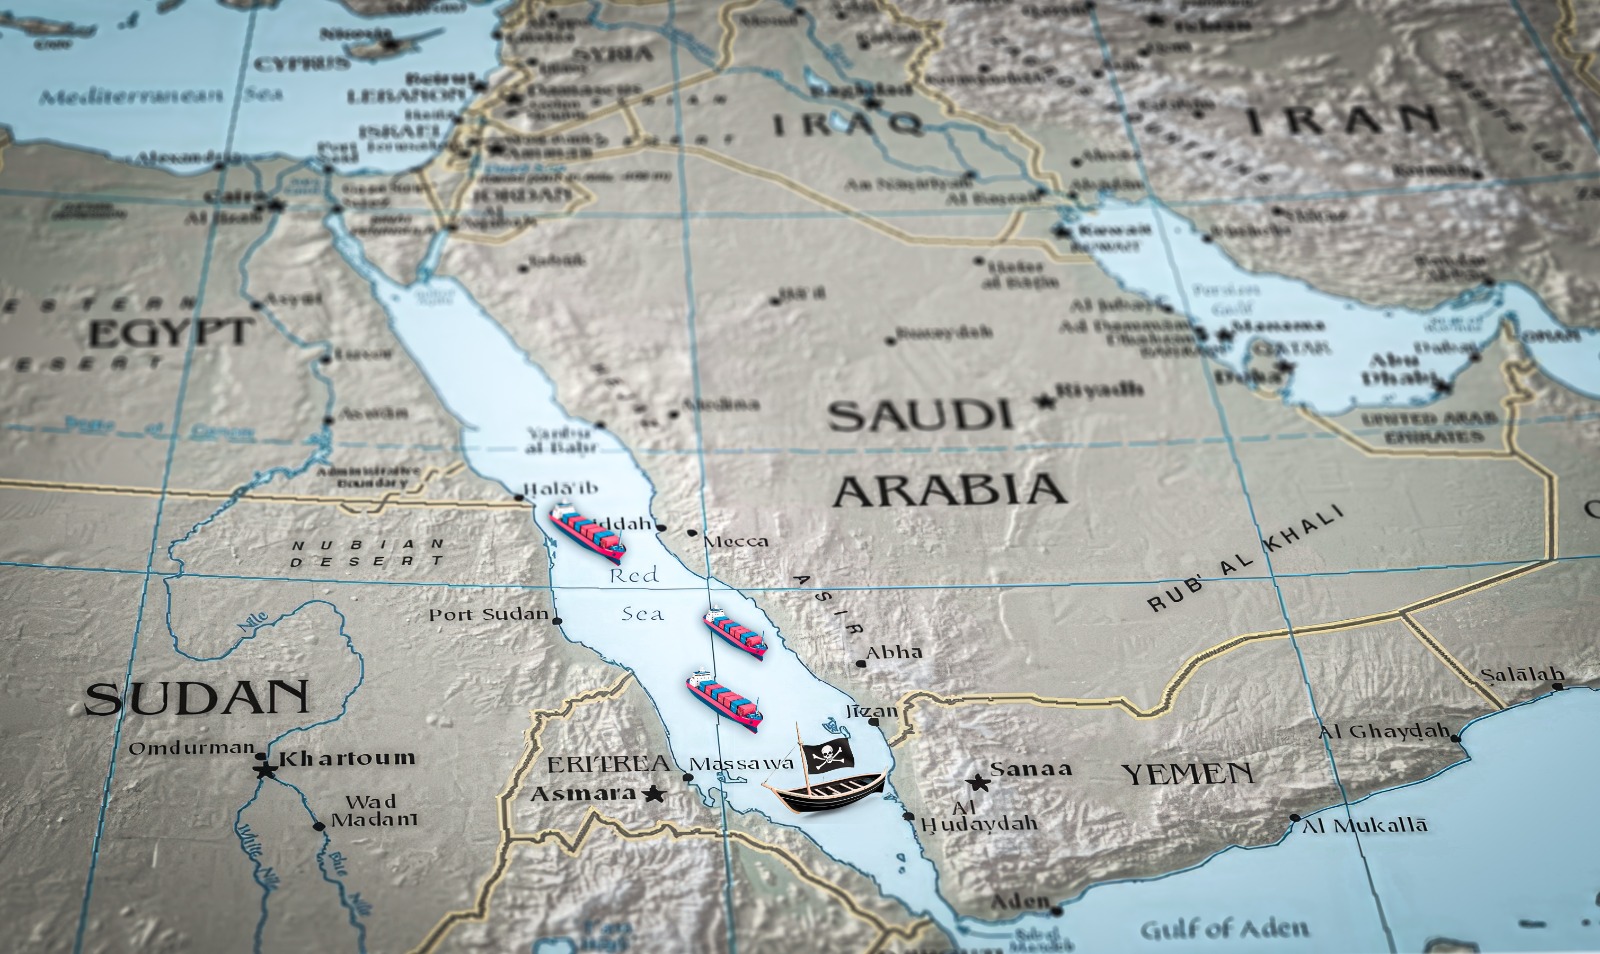
However, the market outlook remains fragile. Houthi attacks, threats involving Saudi Arabia and reports of tanker explosions near the Strait of Hormuz continued to raise questions about the security of regional energy flows. The mixed signals mean that traders cannot yet assume a sustained improvement in supply conditions.
Market data also offered competing influences. US crude inventories fell by 1.9 million barrels, contrary to forecasts for a modest increase, while gasoline stocks rose by 3.9 million barrels despite expectations of a decline. Expectations of stronger Russian output also weighed on prices as refinery activity recovered following a period without confirmed attacks, Reuters reported.
Oil-price movements carry implications beyond energy producers. A sustained rise in crude prices can increase transport, manufacturing and electricity costs, placing pressure on businesses and household budgets. For central banks, energy-driven inflation can complicate decisions over interest rates, particularly when price pressures are already persistent.
Conversely, a durable decline could ease some cost pressures for oil-importing economies, although the benefits would depend on how quickly lower crude prices reach consumers and businesses.
For investors and energy companies, the immediate focus remains on diplomatic progress, the security of shipping routes and evidence of a sustained recovery in supply. Until those risks diminish, oil prices are likely to remain sensitive to both political developments and operational disruptions.