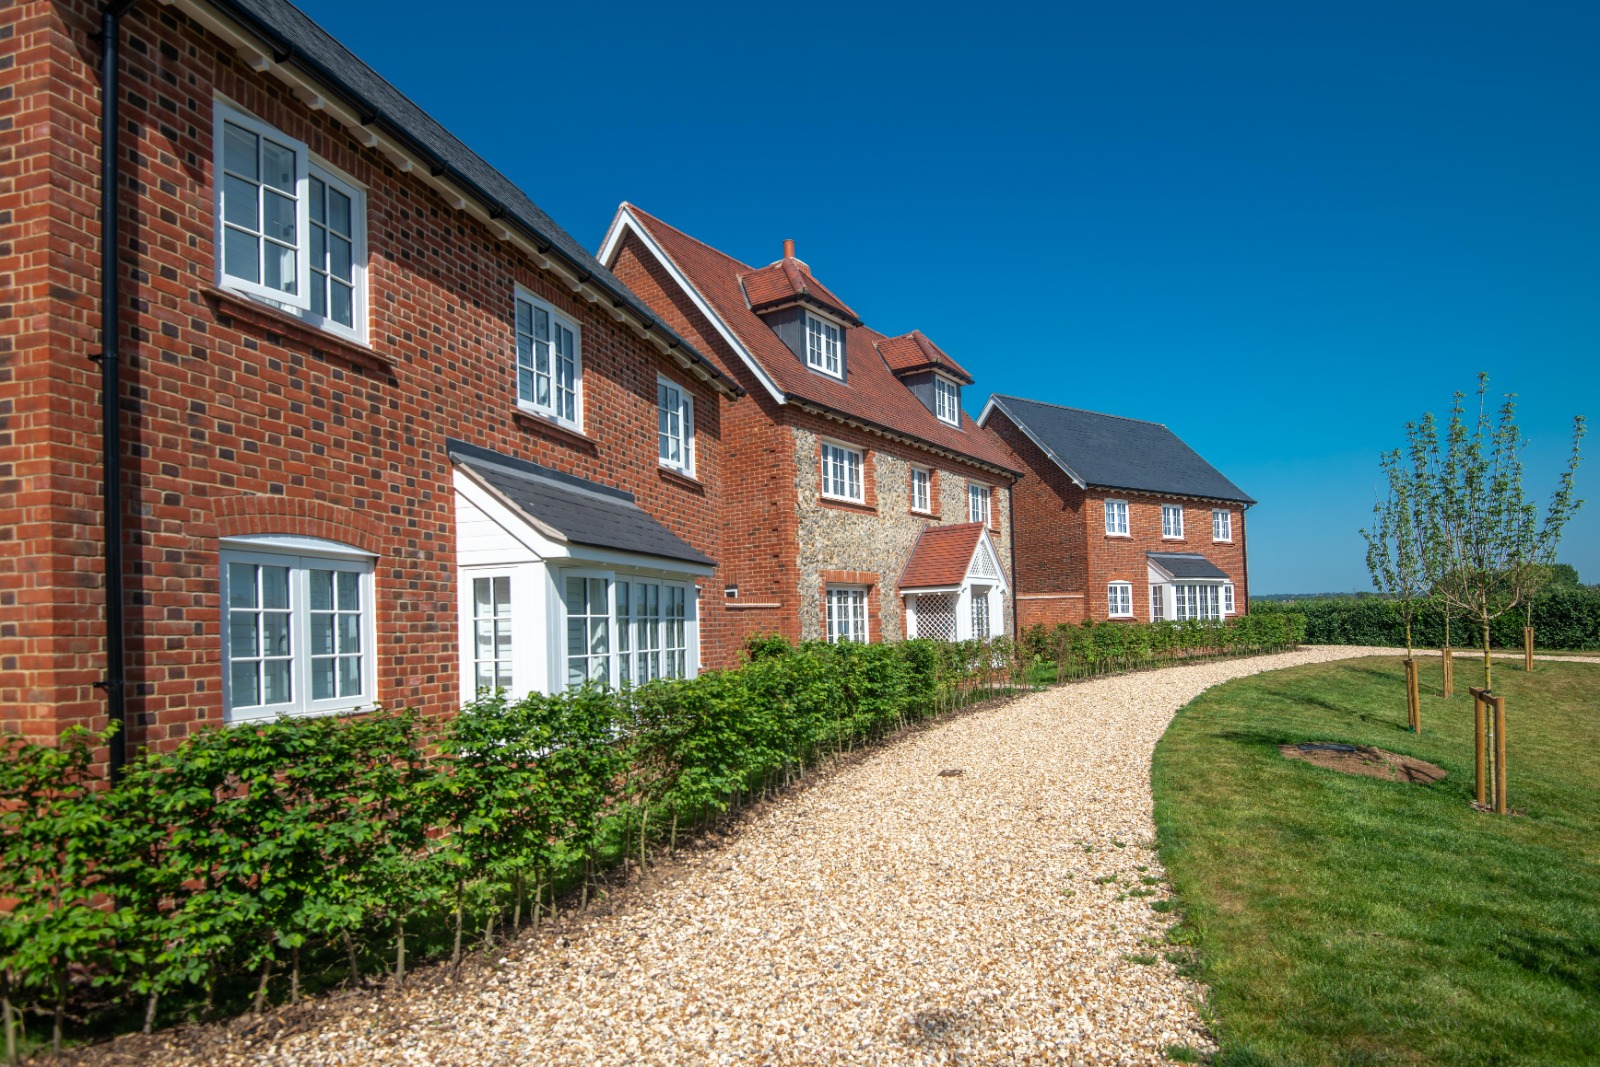
British residential asking prices rose in October, but the increase offered an incomplete picture of housing-market conditions as higher mortgage rates began to weigh on affordability, according to property website Rightmove. The figures suggest that price growth and underlying buyer demand may be moving in different directions.
The average asking price for homes newly listed during Rightmove’s October reporting period, which ran from 13 September to 10 October, increased by 1% from the previous month. That compared with a 0.7% rise in the preceding period. However, the figures are not seasonally adjusted, and asking prices typically increase in October, limiting the extent to which the latest gain can be interpreted as evidence of stronger demand.
The affordability challenge is becoming more significant as mortgage rates rise. Reuters reported that higher borrowing costs, associated in part with the war in Iran, were beginning to affect the housing market, including segments that had previously shown greater resilience. Higher monthly repayments can reduce the amount buyers are able to borrow, forcing households to reconsider property budgets or postpone purchases.
The distinction between asking prices and completed transactions is important for assessing market health. Sellers may maintain ambitious price expectations even as buyers become more cautious. If the gap between those expectations and buyers’ capacity to pay widens, homes can take longer to sell, negotiations may become more difficult and transaction volumes may weaken before asking prices show a substantial decline.
The effects extend beyond households. Estate agents, mortgage lenders, conveyancers, home-improvement businesses and construction companies all depend to varying degrees on housing-market activity. A slowdown in transactions can reduce fee income and delay spending associated with moving home, including purchases of furniture, appliances and renovation services.
For the wider economy, housing affordability also affects labour mobility. Workers may be less able to relocate for employment if mortgage costs or deposit requirements make moving prohibitively expensive. At the same time, households allocating more income to housing have less flexibility for discretionary consumption.
The October figures therefore present a mixed signal. The increase in asking prices indicates that sellers have not broadly abandoned higher valuations, but it does not demonstrate that buyers can sustain those prices under current financing conditions.
Market participants will be watching mortgage-rate movements, agreed sales, transaction volumes and the gap between asking prices and final selling prices. These measures will provide a clearer indication of whether the market is absorbing higher borrowing costs or moving towards a more prolonged slowdown.