Several planned listings linked to the sector have been postponed or paused in recent days. These include a proposed real estate investment trust listing by Blackstone-backed AirTrunk, a fundraising plan involving Nvidia-backed Firmus and a listing associated with SoftBank-backed SB Energy. The setbacks reflect growing caution over valuations, debt exposure and the ability of AI infrastructure businesses to deliver projected earnings.
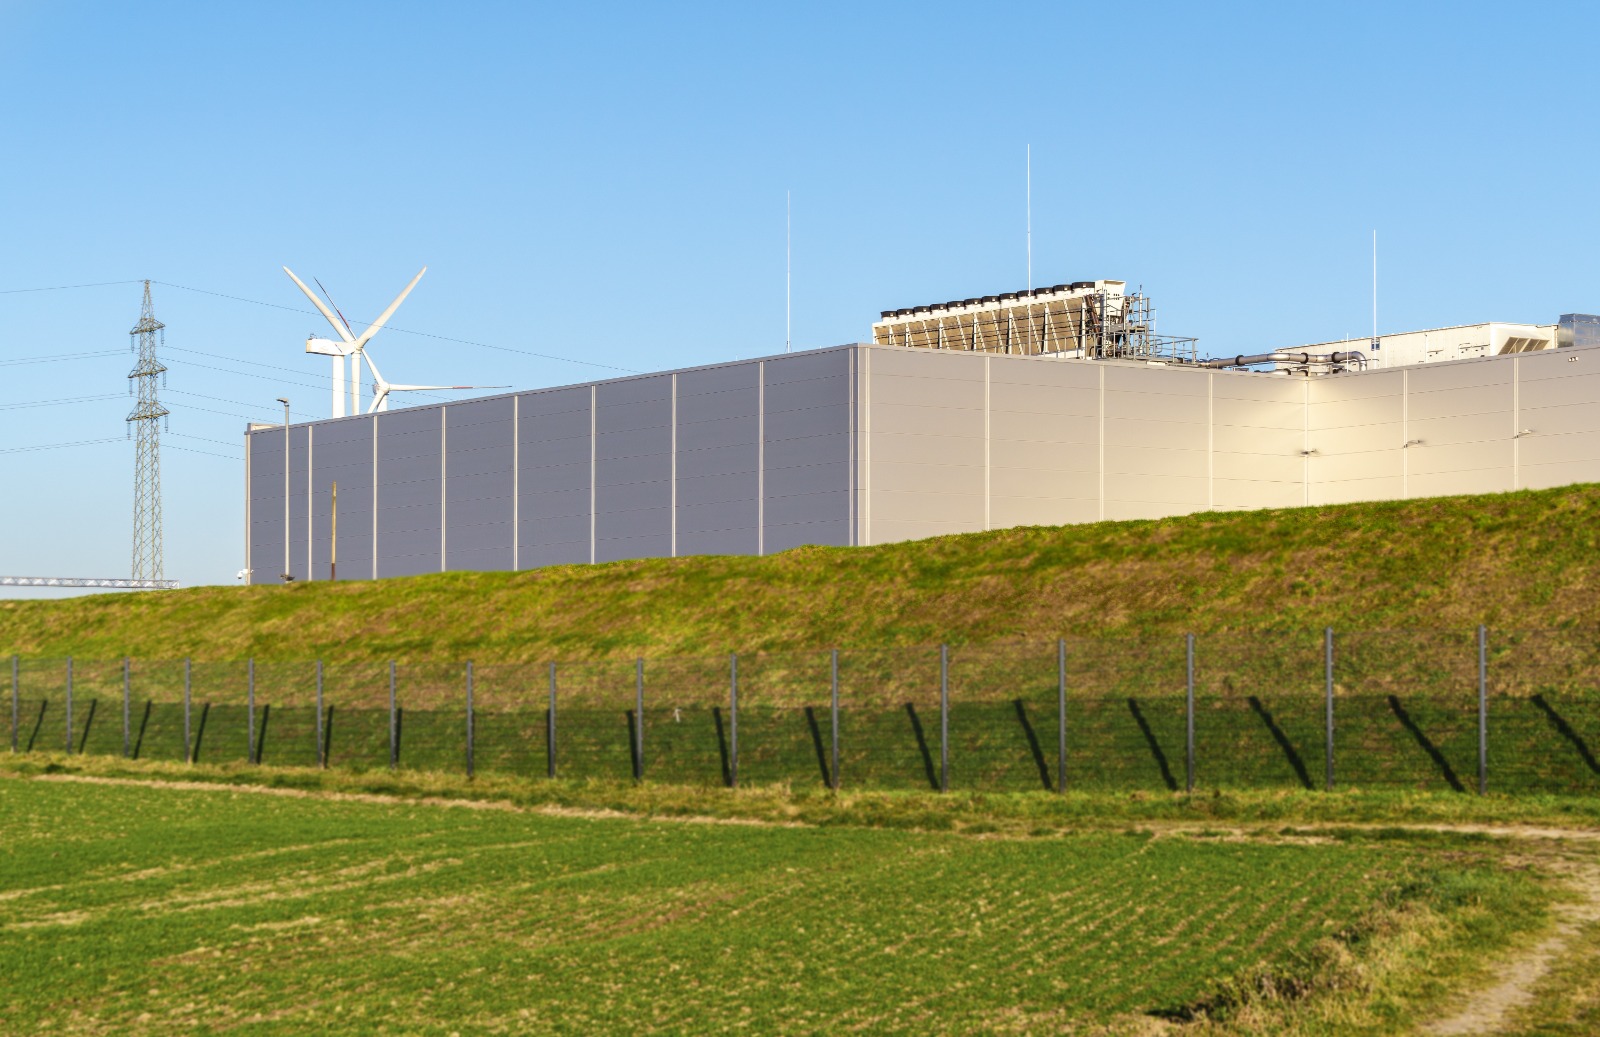
The shift comes after a period of aggressive investment in facilities required to support advanced computing. Data-centre developers must secure land, electricity, cooling systems and high-performance equipment before many projects can generate their expected revenue. Higher interest rates increase the cost of financing these investments and make delays or lower-than-expected demand more consequential.
Firmus had sought to raise $5 billion in what would have been Australia’s second-largest stock market listing, but struggled to convince investors it could meet ambitious revenue projections while carrying about $30 billion in debt, Reuters reported. The example highlights the pressure facing companies whose valuations depend on substantial future growth and continued access to capital.
Nevertheless, investment activity has not stopped. Mergers and acquisitions involving Asian data centres reached $21.3 billion by Tuesday, more than double the $10 billion recorded throughout 2025. Debt financing through syndicated loans and bond issuance totalled $22.3 billion so far this year, while equity fundraising fell 4.6% year on year to $5.4 billion. The figures suggest that investors remain interested but are becoming more selective about how they finance expansion.
Developers also face practical constraints beyond financing. Securing reliable power and suitable land is increasingly difficult in some markets, while concerns about electricity consumption, water use and environmental impact can complicate project approvals.
Established operators with long-term customer contracts may attract stronger investor interest than newer businesses dependent on optimistic forecasts. The distinction could influence which companies expand most rapidly as demand for computing capacity grows.
The sector’s next phase may therefore be shaped less by the scale of announced investment and more by financial discipline, dependable customer demand and the ability to deliver projects on time.