France's 10-year government bond yield rose above 5% on Thursday, reaching a level not seen since 2002. The premium investors demanded to hold French debt rather than benchmark German government bonds widened to nearly 180 basis points, its highest level since the euro-zone debt crisis in 2011.
Bond yields rise when prices fall, meaning the sell-off increases the cost at which a government can borrow from investors. The latest movement reflects concerns about France's substantial fiscal deficit, rising debt burden and political difficulties in securing agreement on measures to improve public finances.
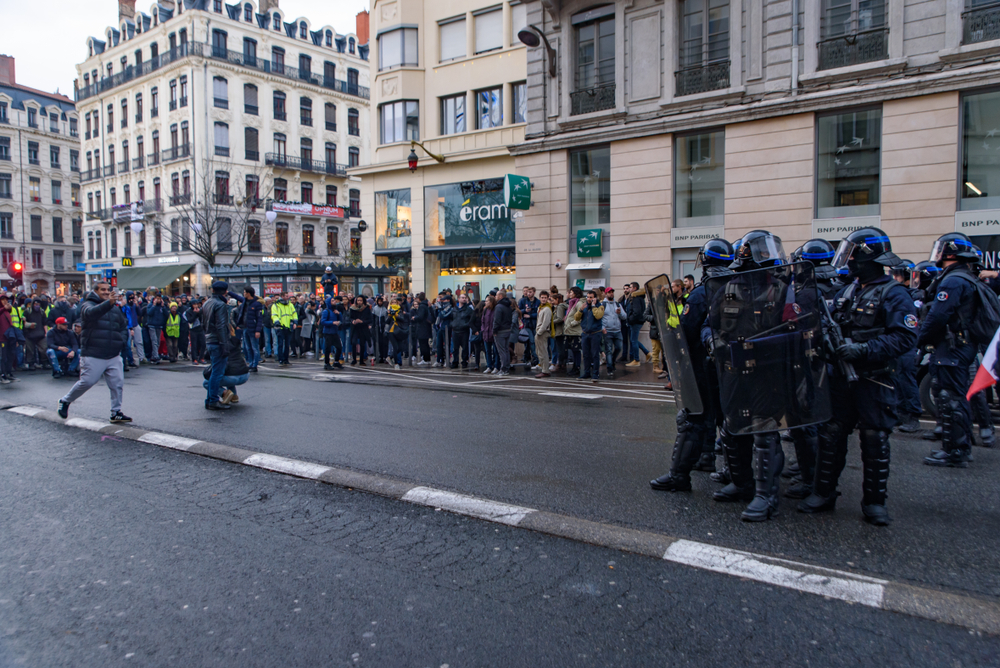
Political uncertainty has added to investor unease. A weakened government faces challenges in advancing its budget plans, while widespread protests and the prospect of a closely contested election next year have increased doubts about the country's ability to deliver a credible fiscal adjustment. These concerns have made French debt more vulnerable to changes in market sentiment.
The widening gap between French and German yields is particularly significant because Germany's Bunds are widely used as a benchmark for euro-area sovereign debt. When investors demand a larger premium to hold French bonds, it signals a reassessment of the relative risks associated with the two governments' borrowing.
The pressure could extend beyond France. Reuters reported that investors were also monitoring Italy, Belgium and Greece, where concerns about debt levels, political developments and social unrest could contribute to higher financing costs. Italian 10-year yields rose during the week, approaching levels last seen in early October.
Higher borrowing costs can gradually increase the expense of refinancing existing debt and servicing new issuance. That may leave governments with less room to fund public services, investment and economic support, particularly if higher interest payments coincide with weaker growth.
The consequences also extend to financial markets. Sovereign yields influence borrowing costs across the economy, including corporate financing and some household loans. A sustained increase could therefore weigh on investment and economic activity.
Investors will be watching France's budget negotiations, political stability and the government's ability to demonstrate a credible path towards fiscal sustainability. Whether the yield premium stabilises or widens further will be an important indicator of confidence in France and the resilience of the wider euro-area bond market.