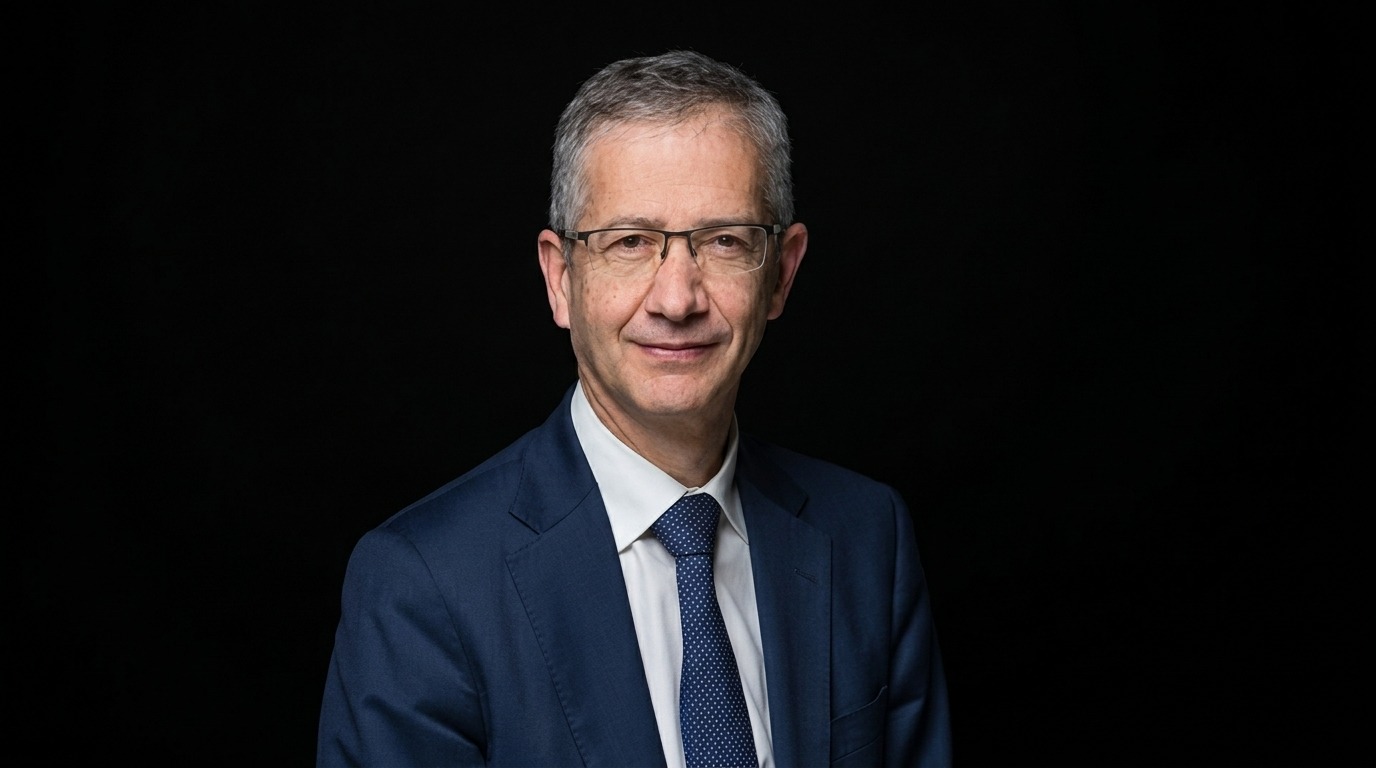
Pablo Hernández de Cos, head of the Bank for International Settlements, said on Thursday that the scale and speed of the current AI investment cycle warranted caution, particularly as financing becomes increasingly dependent on debt and private credit.
The BIS estimates that the world's five largest technology companies are expected to invest more than $1 trillion in artificial intelligence between 2025 and 2026. Broader industry forecasts suggest global AI investment could rise from about $500 billion currently to as much as $4 trillion by 2030.
The spending boom has already reshaped capital flows. Economies deeply integrated into the AI supply chain, including South Korea, Taiwan, Singapore and Malaysia, are benefiting from stronger demand for chips, equipment and digital infrastructure.
But the concentration of investment and rising market valuations have raised concerns that expectations could become detached from underlying returns.
Hernández de Cos said AI financing was increasingly moving beyond traditional corporate earnings towards debt and private credit. The opaque and interconnected nature of some of that financing could amplify vulnerabilities if projected commercial returns fail to materialise.
The concern is not that AI's economic benefits are necessarily overstated. Generative AI has already demonstrated substantial productivity gains in areas such as coding, consulting and professional services. The larger question is whether those gains can translate into sustained economy-wide productivity growth.
Labour markets also face disruption. Evidence of job displacement is emerging in areas including customer service, programming and administrative work, increasing pressure on governments and businesses to invest in retraining.
For central banks, the challenge is particularly complex because AI is simultaneously changing productivity, demand, investment and financial markets. That makes traditional economic relationships harder to interpret.
The AI boom therefore presents a dual opportunity and risk. If investment produces the productivity gains expected by markets, it could support long-term growth. If valuations and financing expand faster than underlying earnings, however, the technology cycle could become a source of financial instability rather than simply an engine of productivity.